
Definitive due-diligence guide · Responsible Sourcing
Responsible Gold Sourcing
A practical guide to supplier checks, traceability, OECD due diligence, conflict risk, AML, and responsible purchasing decisions.
What this guide establishes
- Responsible sourcing is an ongoing risk-management process, not one document.
- Traceability records must be tested against supplier, location, payment, and transport evidence.
- Independent testing supports due diligence but does not verify every social, legal, or financial risk.
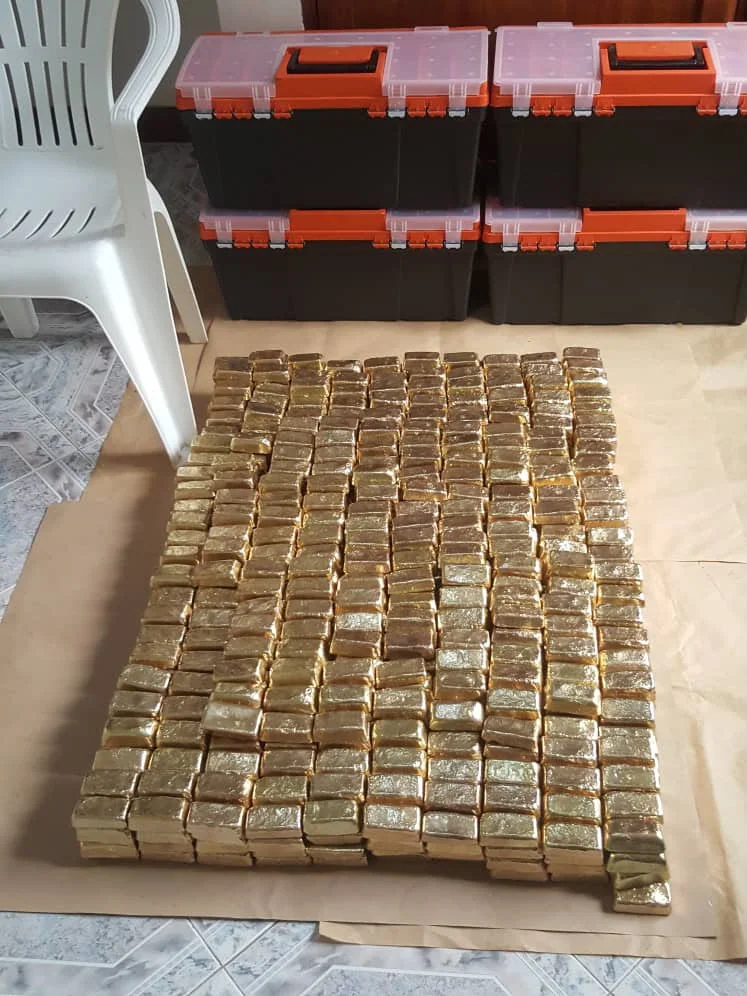
Responsible gold sourcing means identifying and addressing the risks connected to extraction, transport, trade, processing, and payment. It is not a one-time certificate and it is not a promise that every risk has disappeared. It is a documented, risk-based process that helps a company know its suppliers, trace material, assess high-risk circumstances, respond to concerns, and explain what it has done.
What responsible sourcing means
Responsible sourcing is the process of identifying, preventing, mitigating, and accounting for adverse impacts connected to a company's supply chain and business relationships. In gold, risks can include serious human-rights abuse, conflict financing, corruption, money laundering, false origin, and environmental harm.
A buyer needs a repeatable process that distinguishes a manageable concern from a risk that requires suspension or disengagement.
Set a policy, assign responsibility, collect information, assess risks, record decisions, monitor suppliers, and report proportionately.
Policies, supplier files, risk assessments, approvals, monitoring results, corrective actions, and public reporting show how the process operates.
Responsible sourcing does not mean avoiding every high-risk location automatically. It means applying enhanced, documented due diligence.
The OECD five-step framework
The OECD minerals guidance sets out five steps: establish strong management systems, identify and assess supply-chain risk, design and implement a risk response, obtain independent third-party audit at identified points, and report on due diligence.
The framework gives international buyers and refiners a common structure for reviewing suppliers and explaining decisions.
Translate each step into named owners, records, approval thresholds, timelines, and escalation paths that fit the company's position in the chain.
A reviewer should see how information moved from collection to risk decision, mitigation, audit, and reporting.
Copying the five headings into a policy is not implementation. The company must show how controls work in actual transactions.
Supplier identification and verification
Supplier due diligence establishes the legal entity, beneficial owners, authorised representatives, business activity, licences, source relationships, payment details, and relevant history.
A technically genuine parcel may still expose a buyer to serious risk if the supplier or payment path is unclear.
Use independent registries, official licence checks, sanctions and adverse-information screening, references, site information, and direct contact.
Dated search results, verified documents, interview notes, ownership charts, and approval records support the supplier file.
A company certificate confirms registration, not responsible conduct or ownership of the material.
Traceability and chain of custody
Traceability links the material to suppliers, locations, production or collection records, transport, processing, and transfers. Chain of custody records who controlled the material or sample at each stage.
The records help the buyer test whether quantity, origin, route, and timing make sense together.
Use lot identifiers, weight reconciliations, transport records, seals, invoices, photographs, production data, and exception reports.
A defensible file reconciles material in, material out, losses, processing changes, and payment without unexplained gaps.
A long document trail is not automatically reliable. Information must be checked for consistency and credibility.
Conflict-affected and high-risk areas
A conflict-affected or high-risk area may involve armed conflict, widespread violence, institutional weakness, serious abuse, corruption, or other heightened risks. Risk can also arise from a supplier, route, product, or unusual transaction structure.
Geography is a starting point, not the only test. A low-risk label should not excuse obvious entity or transaction concerns.
Use current country information, local context, sanctions, supplier evidence, route analysis, and stakeholder information to determine enhanced steps.
Document the sources used, date of assessment, risk factors, conclusion, reviewer, and monitoring frequency.
Country lists change and can oversimplify local conditions. Decisions should use several credible sources.
AML, KYC, and payment risk
Gold's high value, durability, and portability can make the trade vulnerable to money laundering and other financial crime. KYC identifies counterparties. AML controls assess and respond to the risk that transactions may involve criminal proceeds or prohibited activity.
Payment instructions, beneficial ownership, source of funds, and the relationship between payer, seller, and material need to make commercial sense.
Set risk-based onboarding, transaction monitoring, approval, recordkeeping, and escalation processes appropriate to the company and jurisdiction.
Identity files, ownership records, payment verification, monitoring alerts, approvals, and any required reports support the financial-crime control file.
Laboratory testing does not perform KYC or prove lawful source of funds.
Independent testing within due diligence
Independent testing verifies composition for an identified sample. It can expose material inconsistencies, support weight and purity reconciliation, and provide evidence separate from the supplier's own claim.
The result helps the buyer test whether physical material, seller description, invoice, and expected value are consistent.
Control sampling, custody, laboratory selection, reporting, and direct verification. Link the result to the due-diligence file and transaction decision.
Intake records, sample seals, method details, reports, and reconciliation calculations show how analytical evidence was used.
Testing cannot establish mining conditions, beneficial ownership, payment legitimacy, or export legality by itself.
Risk response and ongoing monitoring
When concerns are found, a company may continue with measurable mitigation, temporarily suspend activity, or disengage, depending on severity, leverage, and applicable rules. Zero-tolerance risks require a different response from correctable record gaps.
The decision should protect people, the company, and legitimate trade without treating every issue as identical.
Define escalation levels, responsible decision-makers, corrective actions, deadlines, evidence required, and monitoring after approval.
Risk committee records, mitigation plans, supplier commitments, follow-up checks, and closure decisions demonstrate accountability.
Commercial pressure should not override unresolved serious abuse, sanctions, ownership, or financial-crime concerns.
Clear answers before the next step.
What Is Responsible Gold Sourcing?
Responsible gold sourcing is a risk-based process for identifying and addressing adverse impacts connected to the supply chain. Adopt a policy, assign ownership, assess suppliers and transactions, and record decisions. One certificate cannot replace ongoing due diligence. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
How the OECD Five-Step Framework Works?
The framework covers management systems, risk identification and assessment, risk response, independent audit at identified points, and reporting. Map each step to named owners and transaction records. A policy that repeats the steps without implementation is not enough. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
What Is a Conflict-Affected or High-Risk Area?
A conflict-affected or high-risk area may involve armed conflict, violence, serious abuse, corruption, institutional weakness, or other elevated risk. Use current sources and assess geography together with entity, route, and transaction factors. No single country list captures every local or changing risk. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
How to Assess a Gold Supplier?
Supplier assessment confirms the entity, beneficial owners, authority, licences, activity, source relationships, and payment path. Verify important information through independent sources and refresh it according to risk. Registration alone does not prove responsible conduct. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
What Records Support Traceability?
Traceability records may include lot IDs, production data, weights, invoices, transport documents, seals, photographs, processing records, and transfer logs. Reconcile quantities and investigate gaps rather than collecting documents without review. A complete-looking file can still contain false or inconsistent information. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
What Is a Gold Supply Chain Policy?
A supply-chain policy states the risks a company will identify, prevent, mitigate, or refuse, together with supplier expectations and escalation rules. Include the policy in onboarding, contracts, training, and monitoring. A policy has little value if commercial teams can ignore it. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
When Should a Buyer Pause a Transaction?
Pause when identity, origin, ownership, licences, payments, documents, route, or testing produce material unresolved concerns. Record the reason, information needed, reviewer, and decision deadline. Do not let urgency turn a pause into unrecorded approval. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
How Independent Testing Supports Due Diligence?
Independent testing can confirm composition for a controlled sample and expose inconsistencies between material and documents. Link the report to sample custody, weight reconciliation, and the transaction risk assessment. Testing does not establish origin, ownership, or lawful payment. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
Does responsible sourcing ban gold from high-risk areas?
The OECD approach supports risk-based due diligence and responsible engagement, with responses based on the nature and severity of identified risks. Apply enhanced checks and a documented response. Some zero-tolerance risks, sanctions, or legal rules may require disengagement. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
What is Dodd-Frank Section 1502?
Section 1502 led to US SEC disclosure requirements for certain issuers using conflict minerals, including gold, when necessary to products they manufacture or contract to manufacture. Affected companies should confirm current obligations with qualified US counsel and SEC materials. The rule does not apply identically to every gold buyer or private company. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
Is traceability the same as due diligence?
No. Traceability provides information about material movement and identity. Due diligence uses that information with broader risk assessment, response, monitoring, and reporting. Test traceability records against supplier and risk evidence. A traceable supply chain can still contain adverse impacts. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
Who is responsible for supplier due diligence?
The company entering the relationship remains responsible for its risk-based process, even when consultants, laboratories, or platforms provide information. Assign internal ownership and approval authority. Outsourcing checks does not outsource accountability. The appropriate response depends on the material, jurisdiction, parties, value, and intended use, so buyers, exporters, refiners, jewellery manufacturers, investors, compliance teams, and public institutions should confirm transaction-specific requirements before acting.
Official and primary sources
Verify requirements at the source.
Government-backed risk-based guidance for companies across mineral supply chains.
US SEC Conflict Minerals RuleOfficial overview of the disclosure rule implementing Section 1502 of the Dodd-Frank Act.
LBMA Responsible Gold GuidanceResponsible sourcing expectations for refiners in the LBMA Good Delivery system.